All Categories
Featured
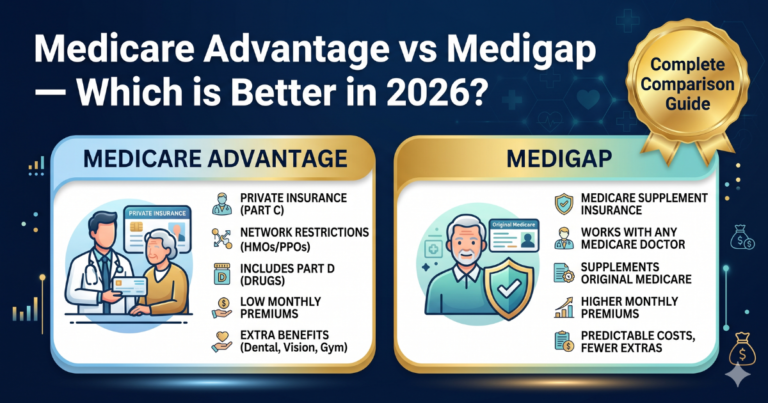

Readying for 2026 Medicare Advantage Selection
As you compare Medicare Supplement insurance coverage plans, believe about how much healthcare you need, how often you go to the medical professional and how much you can manage to pay toward your medical costs yourself. Each Medigap strategy has a different level of protection, so you should discover one that fits your particular requirements.
With Original Medicare (Parts A and B), you are accountable for paying approximately 20% of your health center costs. Medigap plans spend for some or all of your staying costs, depending on your plan letter. The very best Medicare Supplement prepare for you depends on your health and spending plan. Leading plans Part A coinsurance Yes Yes Yes Part B coinsurance Yes Yes Yes Blood transfer (3 pints) Yes Yes Yes Part A hospice care Yes Yes Yes Knowledgeable nursing facility Yes Yes Yes Part A deductible Yes Yes Yes Part B deductible Yes Part B excess charges Yes Yes Yes = 100% Other plans Part A coinsurance Yes Yes Yes Yes Yes Yes Yes Part B coinsurance Yes Yes Yes Yes 50%75% Yes Blood (3 pints) Yes Yes Yes Yes 50%75% Yes Part A hospice care Yes Yes Yes Yes 50%75% Yes Competent nursing facility Yes Yes 50%75% Yes Part A deductible Yes Yes Yes 50%75%50%Part B deductible Yes Part B excess chargesForeign travel emergency80%80%80% Yes = 100% This can offer you comfort because you will not be surprised by high medical costs.
Plans F and C have better protection than Strategy G, however you can't get them if you're a new enrollee. Plus, these strategies may not save you cash because of their high month-to-month rates. Insurance coverage business can utilize your health history if you get a plan outside the six months around your 65th birthday, called the "preliminary enrollment period." If you buy a plan with low protection when you're 65 and later choose to upgrade to something better, such as Strategy G, companies may estimate you a high rate or deny you protection completely.
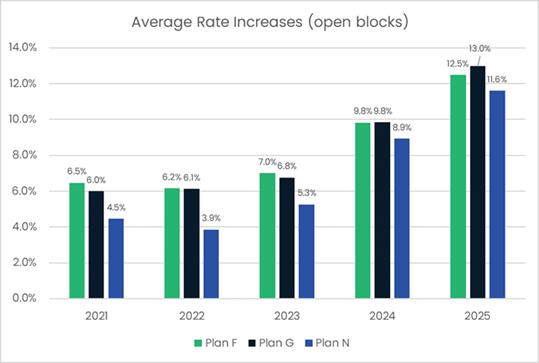
Plan G has the very best protection for the majority of senior citizens and others on Medicare. After you pay this, Plan G will spend for treatment such as medical professional gos to, blood tests or outpatient medical treatment. Pros and cons of Strategy G Popular strategy that covers nearly all of your health expenses Frequently a much better value than Plan F Rates can be costly, at $180 each month, on average Cheaper plans may be a better offer if you hardly ever check out the medical professional Strategy F has the best protection of any Medigap strategy overall.
Insurance in Hemet CAPros and cons of Plan F Spends for nearly all medical expenses High month-to-month rates Not available to new Medicare enrollees Strategy N has similar protection to Strategy G however expenses less. With Strategy N, you need to pay $20 for physician check outs and $50 for journeys to the emergency situation space.
Reviewing PPO Vs HMO Health Insurance for 2026
Benefits and drawbacks of Plan N Yes Covers almost all of the expenses you are accountable for with Medicare Yes Plan N costs about $137 each month, which is $43 monthly less than Plan G Additional costs you're responsible for paying when you visit the doctor might counteract cost savings You might have additional fees if your physician does not accept the costs set by Medicare High-deductible Plan G has the most inexpensive regular monthly rate of any Medigap policy.
Remember, business can charge greater rates or deny protection since of your health history if you change Medicare Supplement prepares outside the 6 months around your 65th birthday. That means you might be stuck with a high-deductible Strategy G when you're older and in worse health, costing you more in the long run.

This implies that Medicare Supplement Strategy G from AARP/UnitedHealthcare offers you the same protection as Strategy G from Aetna, Blue Cross or any other company.

Latest Posts

Term Insurance Options for Seniors in the USA

Selecting the Top 2026 Medicare Supplement Coverage

Exploring IUL Policies for Retirement